Pets & Animals
Is Pet Insurance Worth It? The Answer Hinges on Three Numbers
Whether pet insurance pays off comes down to three numbers: the excess, the annual limit and the pre-existing condition rule. Work out where you stand.

The question is not whether insurance is good
The question that matters to a household considering pet insurance is not whether insurance is a good thing in principle. It is a narrower and more answerable question: would this particular policy actually pay when something happens to this particular animal? That question has an answer, and the answer is found in the policy document rather than in the premium.
Premiums receive almost all of the attention, and they are the least informative part of the comparison. A cheap premium attached to a policy that excludes the conditions a pet is likely to develop is a worse instrument than a higher premium attached to one that pays. Three numbers decide which policy a person is actually holding: the excess, the annual limit, and the rule on pre-existing conditions. This article works through all three, explains the payment mechanic that surprises most new policyholders, and sets out the alternative case for self-insuring, because that case is legitimate and deserves a fair hearing. For the household decisions that sit away from paperwork, the site’s guide to chew toys and destructive chewing covers the behavioural half of living with an animal.
A second framing deserves equal weight. Insurance is a transfer of risk, and the question for a household is not whether the transfer is fair in general but whether this particular risk is one it can carry without cover. Some households can absorb an unexpected bill; others would meet it with a credit card and months of repayment. The policy is priced somewhere between those two positions, and reading it properly is how a household works out which one it is in.
How pet insurance actually pays
Most pet insurance in Australia is a reimbursement product, and a household should understand that before comparing anything. The owner pays the veterinary practice in full at the time of treatment. The insurer then reimburses the covered portion afterwards, minus the excess and subject to the limit. The policy does not settle the bill with the vet; it returns money to the owner later.
The cash-flow implication is worth stating plainly, because the community discussions return to it constantly: a policy does not solve not having the money on the day. Where a household would struggle to find a few thousand dollars at short notice, that difficulty exists with or without insurance, and the policy’s benefit arrives after it rather than during it. The second half of the mechanic concerns payment plans. Veterinary practices generally do not offer them, for the same commercial reason any business declines to extend credit: the practice still carries the cost of the treatment, and unpaid accounts are a real burden on veterinary businesses. Neither fact makes insurance bad. Both facts belong in the decision, and neither appears in the advertising.
The mechanics of a claim follow from the same structure and are worth knowing before the first one. The owner keeps the treatment invoice and the clinical history, submits both to the insurer, and waits for an assessment. The process exists because insurers verify what they pay, and it means the money returns after a sequence of steps rather than at the counter. Households should plan the cash flow around that sequence rather than against it.
Two practical consequences follow. The first is that documentation is the currency of a claim: an itemised invoice and a complete history are what turn a submission into a payment, and a household that asks the treating practice for both at the time avoids a round of correspondence later. The second is that the covered portion and the total bill are different numbers. A policy pays against its own schedule of what it will cover, and the gap between that schedule and the invoice is the owner’s to hold. None of this is a reason to avoid the product. It is the fine print of how the product operates, and it is knowable in advance.
Number one: the excess
The excess is the amount the owner pays towards each claim before the insurer pays the rest, and it comes in two shapes that are easy to confuse.
The first is an excess applied per claim or per condition. The second is an excess applied per policy year. The distinction sounds administrative and becomes significant the moment a condition is lifelong. Under a per-condition excess, a chronic condition, such as arthritis or a heart condition, attracts the excess again in each year of treatment. Under a per-year excess, every covered condition in that year sits behind the same single amount. For a young animal with one-off injuries, the difference may be modest. For an older animal with an ongoing condition, it compounds annually, and it is the first thing to locate in the Product Disclosure Statement before comparing two policies on price.
A worked contrast makes the shape concrete. Take a dog who tears a ligament at two and later develops arthritis in the same joint. Under a per-condition excess, those are two conditions and two excesses across the years. Under a per-year excess, several treatments inside one policy year sit behind a single deduction, which can favour the household in a heavy year and cost it in a light one. Neither structure is dishonest; they distribute the same costs differently. The mistake is buying one while imagining the other, and the fix is to locate the clause and read its shape before the premium decides anything.
Number two: the annual limit
The annual limit is the most the insurer will pay in a policy year, and the critical question is not the size of the limit but its shape: is it a single limit covering everything, or a limit per condition?
The contrast can be worked without quoting a dollar figure. Consider two policies with limits that look identical on the comparison page. Under the first, the limit is shared: three separate problems in one year draw on one pool, and the third problem arrives at a pool that two claims have already reduced. Under the second, each condition carries its own limit, so the three problems draw on three pools. The same year of misfortune produces very different outcomes from two instruments the buyer reasonably believed were equivalent. Sub-limits add a further layer: a policy may impose a lower cap on specific categories, such as tick paralysis or specialist imaging, regardless of the headline limit. These figures live in the PDS, and locating them is the exercise.
Sub-limits deserve their own paragraph, because they are where a claim that looked covered lands. A policy can carry a generous headline limit and a much tighter cap on particular categories: specialist imaging, tick paralysis, behavioural treatment, or conditions a schedule names individually. The headline figure is also the number most often quoted in advertising, while the sub-limits sit several pages into the document. The comparison discipline is therefore to read down from the big number rather than stopping at it, and to ask directly, in writing, what the smaller caps are.
Number three: the rule on pre-existing conditions
This is the condition behind the loudest complaint in every forum discussion, and it is not hidden so much as unread. A condition that showed signs or symptoms before cover began, or during any waiting period attached to the policy, is generally treated as pre-existing, and a pre-existing condition is typically excluded for the life of the animal, not merely for its first year.
Three details follow from that. The clock matters: the rule runs from the first sign of a problem, not from the diagnosis, so a limp investigated last spring is on the record even if its cause was only named later. The waiting period matters: a condition that appears in the first weeks of a new policy sits in the same excluded category as one that appeared before it. And the permanence matters most of all: where the exclusion applies, it applies for the lifetime of the condition, which is why cover begun while an animal is young is structurally different from cover begun later. This is the mechanism behind the advice that circulates in owner communities, to insure a young animal and decide whether to continue later; it is presented here as what the policies do, not as a recommendation for any household’s decision.
Why insurers structure the rule as they do is worth understanding, because it removes some of the sting. Cover bought the day after a symptom appears would be a promise to pay a known cost, not insurance against an unknown one, and the mathematics of a pool cannot survive buyers who join only once they are certain to claim. The rule exists to keep the product priced for everyone in it. The practical counterpart for a household is simple: insure while the animal is well, and have the health picture at the time of joining recorded properly, because that record is what a later claim is measured against.
The self-insure alternative, stated fairly
The other half of the discussion, and the one that deserves an honest hearing, is to skip the policy and set the equivalent amount aside in an account of its own, with a maximum spend decided in advance for the animal’s care. Done with discipline, this strategy keeps everything: the money, the interest, and the flexibility to spend it on whatever treatment is chosen rather than whatever a policy schedule covers.
Two conditions are needed for it to work. The first is actual discipline: money set aside and then quietly absorbed by ordinary spending is not self-insurance, it is the absence of a decision. The second, and more important, is the honest test at the centre of the whole question: would an unexpected veterinary bill of a few thousand dollars cause genuine financial distress? Where the answer is yes, insurance is doing a real job for that household, whatever the arithmetic of averages says. Where the answer is no, the case for a policy is weaker, and the case for a dedicated account is stronger. Both positions are reasonable, and they belong to the household, not to any insurer or to this article.
A middle path exists between the two extremes, and it is where many thoughtful households land. Some policies allow a higher excess in exchange for a lower premium, which keeps cover for the large events while accepting the small ones as self-funded. That strategy works when the household genuinely holds the excess amount somewhere it can reach, and it fails when the higher excess is chosen purely because it lowers the monthly figure. The test is the same one as before: can the money be found on the day it is needed?
How to compare two policies in twenty minutes
The comparison reduces to a short table, and every row is answered by the Product Disclosure Statement.
| What to check | What to find in the PDS |
|---|---|
| The excess, and its shape | A fixed amount per claim or condition, or per policy year |
| The annual limit | One shared limit, or a limit per condition, and any sub-limits |
| The pre-existing condition rule | What counts, when the clock starts, and the waiting periods |
| Outright exclusions | Routine care, dental, elective procedures, hereditary conditions for some breeds |
| Premium behaviour | Whether the premium rises with the animal’s age, and cancellation rules |
| The payment flow | Whether the owner pays the vet first and waits for reimbursement |
Reading a policy document for its limits and its exclusions is the same discipline the site applies to the NDIS price guide: the structure of the document is where the answer is, and it repays being read before it is needed rather than after. Twenty minutes with two PDS documents beside each other resolves more than any number of premium quotes.
One last discipline for the comparison: write the three numbers down for each policy, side by side, before reading reviews or commentary. The written comparison is boring and slow, and it is the only place the shapes of the two instruments sit still long enough to be seen. Everything after that is preference. The numbers are the decision.
The three numbers to check
The premium is the wrong number to compare, and the arithmetic of averages is no better a guide. What decides whether a policy pays is the excess and its shape, the annual limit and its shape, and the pre-existing condition rule with its clock and its waiting periods. Everything else in the decision follows from those three, plus the household’s own answer to the distress test.
Two boundaries belong at the end. This is not financial advice, and it is not a veterinary opinion; a veterinarian who knows the animal is the right person for questions about its health, and the Product Disclosure Statement is the authority for what any policy does. Where a dispute with an insurer arises, the Australian Financial Complaints Authority handles insurance disputes. The work this article can do is move the decision off the premium and onto the three numbers that decide it.
Sources: Australian Securities and Investments Commission – insurance and Product Disclosure Statements · Australian Financial Complaints Authority – insurance disputes · Australian Veterinary Association – pet care cost guidance · RSPCA Australia – pet ownership costs





Pets & Animals
What a Dog Costs in Year One, Before the Vet Bills Start
A dog’s first year in Australia: adoption or purchase, desexing, vaccines, council registration, food and gear. Build your own budget before the dog comes home.

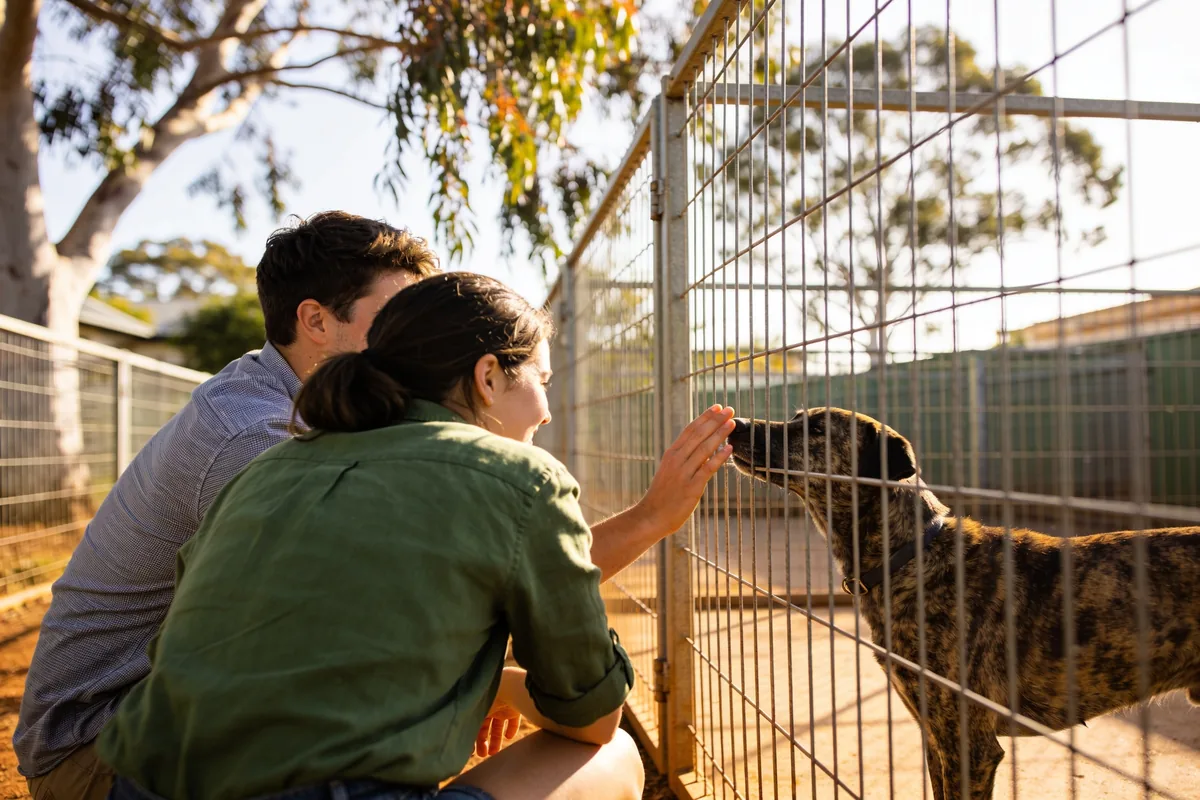
Saturday, a little after nine, and the shelter car park is already half full. Along the outdoor kennel run the dogs have opinions about everyone: a kelpie cross spinning in tight circles, an old staffy lying flat with one ear up, a brindle mutt of no fixed ancestry pressing its nose to the wire whenever anyone slows down. A young couple has slowed down. She is crouched at the mesh, he is reading the laminated card clipped to the gate, and the card carries a name, an age, a temperament note and an adoption fee. They are doing the sum the card invites, which is whether that one number fits. Nobody on the run is asking the other question, the one that decides how the next twelve months feel: what does the rest of the year cost?
The card shows the price of the first afternoon. The calculator below is for the other 364 days. Fill in what you know, leave blank what you do not, and the total grows as you go.
Your dog's first year: a budget
Enter your own quotes and prices. Leave a line blank if it does not apply.
Enter each price you have been quoted. The calculator needs JavaScript to add them up.
Most shelter adoptions include desexing, vaccinations and a microchip. Check your adoption contract.
Enter your own prices to see the first-year total.
For reference, RSPCA NSW's approximate guide puts food at about 600 dollars a year and desexing at 350 to 650 dollars. Your own quotes will differ.
The one-off costs
Go back to the couple at the wire, and imagine they had come to a breeder’s front yard instead. The puppy would be just as appealing. The list of things still to be done to it would be much longer.
The one-off costs are the ones paid once, mostly in the first few weeks, and they arrive in a cluster. RSPCA NSW publishes an approximate guide to them, and it describes its figures as purely a guide; your own vet and council will quote their own. On that guide, desexing runs from about $350 to $650, depending on the dog’s age, sex and size. Council registration ranges from about $23 to $201, with the lower end for a desexed dog and the upper end for one that is not. A bed or a kennel adds roughly $100 to $200.
Then there are the lines without a neat range attached here: microchipping, and the course of puppy vaccinations that a young dog needs in its first months. Ask the vet for both figures at the first visit, and put them in the calculator rather than guessing.
None of this is unusual or unfair. It simply all falls in the same month, which is why it feels like more than it is.
Adopt or buy: where the lines come off
Here is where the couple at the wire are in a stronger position than they probably realise.
RSPCA NSW notes that a dog adopted from it arrives already desexed, vaccinated, microchipped, wormed and flea-treated. In budget terms, several of the most expensive one-off lines come off the list before the dog leaves the kennel. Other shelters and rescues set their own terms, so the adoption contract is the document to check, but the pattern is common.
A puppy bought from a breeder usually arrives with those lines still to be paid. Desexing, the vaccination course and a microchip go onto the household’s bill, on top of the purchase price.
Which is why the old assumption, that buying is somehow cheaper than adopting once the fee is compared, so often falls apart. The adoption fee looks like the bigger number on a card. Add the year up and the picture changes. The calculator handles this automatically: choose “Adopted” and the desexing, microchip and vaccination rows disappear and count as zero, with a reminder to check the contract.
The running costs
The weeks pass. The new bed has been chewed at one corner, the lead hangs by the back door, and the dog has worked out exactly what time dinner is supposed to happen. This is where the year’s real money goes: not in a lump, but in small, steady amounts that are easy to stop noticing.
RSPCA NSW’s approximate guide sets them out. Flea, worm and heartworm prevention comes to about $200 to $300 a year. Food and bowls come to about $600 a year. An annual vaccination and vet check starts from around $140. Grooming, for the breeds that need it, runs from about $70 to $150 a visit, and some breeds need up to six visits a year, which can quietly become the largest line on the list.
Add those together for a dog that is past its first year, and RSPCA NSW’s approximate guide puts the minimum for each consecutive year at about $1,260 to $1,870. That is a floor, not an average, and it assumes nothing goes wrong.
In the calculator, food is entered by the month, because that is how most people buy it. Grooming is split into a price per visit and a number of visits, because a short-coated dog and a poodle cross live in different financial worlds.
Putting the guide’s numbers together
To see how the lines stack up, take an illustration rather than a real household: an adult dog, adopted, short-coated, living under a council with a middling fee. These are not quotes, just RSPCA NSW’s approximate guide figures dropped into the calculator to show the shape of a year.
Because the dog is adopted, desexing, the microchip and the first vaccinations sit at zero. The adoption fee goes in at whatever the card said. Registration goes in at the council’s figure, which for a desexed dog sits towards the lower end of the guide’s $23 to $201 range. A bed lands somewhere in the $100 to $200 bracket.
On the running side, food at about $600 a year works out to roughly $50 a month. Parasite prevention adds $200 to $300, and the annual check starts from around $140. The short coat means grooming stays at zero, and that one fact keeps the running total close to the guide’s floor rather than well above it.
Now swap the short coat for a breed that needs the groomer six times a year at $70 to $150 a visit. That line alone adds $420 to $900 a year, which can match or beat the whole food bill. Same shelter, same Saturday, a very different number by December.
Registration is not optional, and it varies
Somewhere in the first few weeks a reminder arrives, or a neighbour mentions it over the fence, and registration moves from the back of the mind to the front.
It is required, and the price depends on where you live. Council fees differ from state to state and from council to council, and they also depend on whether the dog is desexed. That is the single figure on the list that you can confirm in five minutes, on your own council’s website, before the dog comes home. Do that, and type in the real number.
One more wrinkle worth knowing: some councils register a dog annually, and some register it for life. The calculator assumes registration renews in year two. If yours registers for life, take it out of the year-two figure.
The gear nobody budgets
Then there is the trip to the pet shop, and the second trip, and the parcel that arrives the following week.
A lead and a harness. A collar with a tag. Bowls, if the food line did not cover them. A crate, for some households. A few toys, of which the dog will love exactly one. And, for many first-time owners, a training class, which is often the best money spent in the whole year.
This is the line that varies most from house to house, so the calculator leaves it entirely to you. Be honest with it. If you already know you are the kind of person who will buy the cute raincoat, put the raincoat in.
Be choosy, too. A good toy does more than fill a basket: the right one can save a skirting board, and our piece on how puzzle toys stop a dog's destructive chewing explains why a single well-chosen one is worth more than a pile of squeakers.
The line this article leaves out
At some point in most dogs’ lives there is an evening in an emergency waiting room, a dog panting on a towel, and a quote on a clipboard that nobody had planned for.
That is the cost this article deliberately does not count. Illness, injury and emergency treatment are real and can be large, but they are a different decision with its own arithmetic: whether to insure, or to save, or to accept the risk. We have covered that question separately in whether pet insurance is worth it, and it is worth reading before the dog comes home rather than after the first visit to that waiting room.
The calculator says so on every result. Its total is the cost of a year in which nothing goes wrong.
Questions people ask at the kennel gate
Is the adoption fee the whole cost of adopting? No. It covers the work the shelter has already done, which at RSPCA NSW means desexing, vaccination, microchipping, worming and flea treatment. Registration, food, gear and the running costs are still yours from the first day.
Is a puppy from a breeder dearer in the first year? Usually, because the puppy vaccination course, desexing and a microchip are all still to be paid on top of the price. An adopted dog has most of those behind it before it gets in the car.
Why does registration cost so much more for some dogs? On RSPCA NSW’s guide, where a dog falls between about $23 and $201 depends heavily on whether it is desexed, and then on the council. Your own council’s page will show its figures in a few minutes.
Does the second year really cost less? On the guide’s numbers, yes, because the one-off lines fall away. What is left is the running list, and RSPCA NSW puts the minimum for each later year at about $1,260 to $1,870. A coat that needs a groomer, or a dog that eats like two, pushes that up.
What can wait until year two
Back at the shelter, the couple have moved on to the next kennel and come back again, the way people do. The brindle dog has not taken its nose off the wire. Whatever they decide, they will make a better decision with the year’s number in front of them than with the card’s.
If that number comes out higher than you hoped, there are lines you can trim, because a dog’s first year does not need to look like a shop window. Skip the designer bed; the dog will choose the couch anyway. Skip the third harness, bought because the second one came in a nicer colour. Skip the premium toy subscription that sends a box every month whether the dog needs one or not. Skip anything with “luxury” printed on the packet.
What you should not skip is the dull part: the vaccinations, the parasite prevention, the registration and good food. Those are the lines that keep year two as calm as year one.
Sources: Cost of Owning a Pet, RSPCA NSW (https://www.rspcansw.org.au/information-and-advice/caring-for-animals/costs-of-owning-a-pet/); What do I need to know before I get a new pet?, RSPCA Knowledgebase (https://kb.rspca.org.au/categories/companion-animals/choosing-a-pet/what-do-i-need-to-know-before-i-get-a-new-pet)
Pets & Animals
How Puzzle Toys Stop Your Dog’s Destructive Chewing
Destructive chewing usually means boredom, teething or stress. Puzzle toys redirect it by giving a dog a job to solve, and they work best on a simple routine.

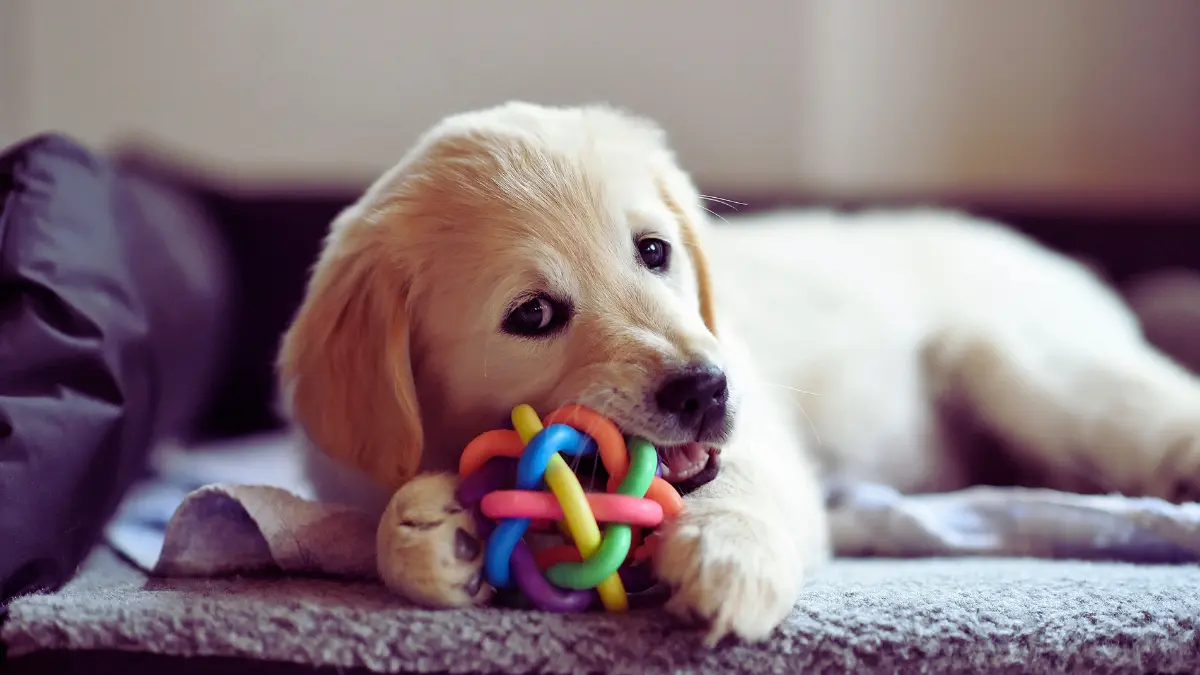
Chewing is what dogs do. When it lands on a shoe or the corner of a couch, it stops being normal and starts being expensive, and the dog gets a reputation they do not deserve. Destroyed cushions are rarely the work of a naughty dog. They are usually the work of an under-stimulated one.
The fix is not punishment, which mostly teaches a dog to chew somewhere you cannot see. The fix is redirecting the energy, and puzzle toys are one of the most reliable tools for doing it.
Why Dogs Chew
Before you can redirect a behaviour, it helps to know what is driving it. Dogs chew for a handful of reasons.
Teething. Puppies chew to relieve the discomfort of adult teeth coming through. It is a phase, but a destructive one while it lasts.
Boredom. A lack of mental exercise leads to frustration, and chewing is a self-soothing way to let some of it out.
Anxiety or stress. Dogs with separation anxiety often chew objects for comfort, and the chewing tends to happen shortly after you leave.
Natural instinct. Dogs explore the world through their mouths. Chewing helps them work out texture, scent and how things come apart.
The urge itself is not the problem. Left with nothing they are allowed to chew, dogs will find something they are not.
How Puzzle Toys Help
Puzzle toys channel the chewing instinct into a job. Instead of punishing the behaviour, they give the dog something to solve, and a dog with a problem to work on is a dog that is not rearranging your furniture.
They provide mental enrichment. Dogs need more than a walk. Puzzle toys make them think, explore and solve, and mental work tires a dog in a different and deeper way than physical exercise alone.
They redirect chewing onto something safe. Many puzzle toys are built from durable, chew-resistant materials, chosen so the dog can work on them for months without swallowing pieces.
They reduce stress. Working through a puzzle and earning a treat creates a calm, positive frame of mind, which is exactly what an anxious chewer needs at the moment the behaviour would normally start.
They slow down eating. For dogs who inhale their dinner, puzzle feeders stretch a two-minute meal into ten minutes of work, which is better for digestion and better for the day.
Signs It Is Working
You will know it is making a difference when your dog:
- Chews fewer household items
- Settles more calmly on their own
- Looks content and tired after a puzzle session
- Waits for puzzle time with enthusiasm
With regular use, many owners notice better impulse control around things the dog should not touch, simply because there is something better to do.
How to Get Started
Begin with one or two puzzles that match your dog’s size and chewing style, and fill them lightly at first so the game is easy to win. Rotate the toys through the week so they stay novel, and put a food-stuffed one down before you leave the house, because the first half hour alone is the hardest part of the day for an anxious chewer.
If the chewing comes with other signs of distress, such as howling, pacing or accidents, talk to your vet. Anxiety needs more than a toy, and it is easier to address early.
Turning the Chew Drive Into a Game
Destructive chewing is a behaviour problem with a kind solution: give the dog work worth doing. Puzzle toys turn the chewing drive into a game the whole household wins, and the couch gets to stay in one piece.
Sources: Australian Veterinary Association, behaviour and enrichment guidance.


 Home & Garden1 year ago
Polycarbonate Roofing: What It Is Good For, and What It Is Not
- Travel1 year ago
Getting Involved in Alice Springs: Clubs, Events and Community Groups
- Healthcare1 year ago
Plantar Warts: The Treatment Ladder, From Patience to Surgery
- Healthcare1 year ago
GP Chronic Condition Management Plans: How Medicare Funds Ongoing Care (the plan formerly called EPC)
- Healthcare1 year ago
Heel Pain: Five Causes, One Order of Treatment
- Healthcare1 year ago
The Role of Speech Therapy in Treating Common Speech & Language Disorders
- Healthcare1 year ago
Laser Treatment for Nail Fungus: What It Involves and What the Evidence Says
- Travel11 months ago
The Ultimate Family Guide to Uluru: Fun Things to Do, Where to Stay & What to Pack